The Federal Government has reduced the interest rate charged on late payment of taxes, with the new regime taking effect from October 1, 2026.
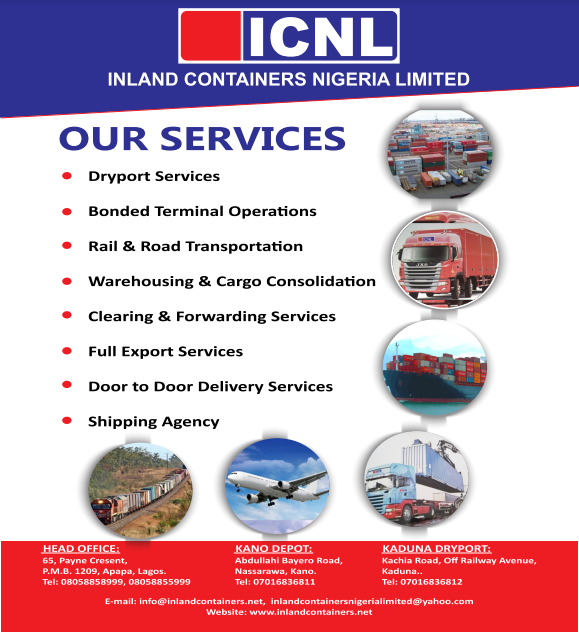
The Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, issued the Nigeria Tax Administration (Interest on Late Payment of Tax) Order, 2026, pursuant to Section 65 of the Nigeria Tax Administration Act, 2025.
The new order applies uniformly to tax authorities at the federal, state and Federal Capital Territory levels.
Under the new arrangement, interest on tax payable in naira will be calculated at the Central Bank of Nigeria’s Monetary Policy Rate (MPR) plus one percentage point, replacing the previous five-percentage-point spread.
However, the applicable rate will not fall below the yield on 364-day Treasury Bills, reflecting the government’s cost of funding when tax payments are delayed.
For taxes payable in foreign currency, the interest rate will be based on the Secured Overnight Financing Rate (SOFR) plus six percentage points. Where SOFR is discontinued, its official successor rate will apply.
The Federal Government said a single rate will apply for each calendar month, with the Nigeria Revenue Service directed to publish the applicable rate on its website by the third business day of every month.
Oyedele said the new framework was designed to align the cost of late tax payments more closely with prevailing market rates.
“Tax that is due belongs to the public. When it is paid late, Government may have to borrow to fill the gap, and the cost falls on everyone,” the minister said.
He added that the new system would provide taxpayers with greater certainty by allowing them to know the applicable interest rate in advance.
The ministry said the new rates would apply to interest arising from October 1, 2026, including interest on taxes that became due before that date.
However, interest that arose before October 1 will remain governed by the rules applicable at the time.
The new order also supersedes the 2017 notice on interest on unpaid taxes and other earlier notices on the subject.
The ministry clarified that the order does not alter the 10 per cent penalty for late payment provided under Section 65 of the Act. Tax authorities also retain the power under Section 66 to waive penalties or interest where good cause is established.
The government urged taxpayers to file their returns and pay applicable taxes on time, while those with outstanding liabilities were advised to settle them promptly or engage the relevant tax authority.


One Comment